Denied claims / Tile or historic

Tile or historic roof claim denied?

Tile roofs are expensive, so insurers look hard for reasons to pay for a few tiles instead of a roof. Cracked tile gets called old, and "just replace the broken ones" ignores whether matching tile even exists.

Why tile or historic claims get denied

These are the denial and underpayment reasons we see most on clay, concrete and historic tile roofs.

"Cracks are pre-existing"

The adjuster says broken tiles were cracked before the storm, from foot traffic, settling or age.

What we do: Fresh breaks look different from old ones: clean, unweathered edges and no dirt or growth in the crack. We photograph each one close up and tie them to the storm date.
"Repair only a few tiles"

The insurer pays to swap out the broken tiles, even when matching tile can't be found or the old tile breaks when you walk it.

What we do: We document how many tiles break during a careful repair, and source matching tile. If no match exists, that goes in the repair scope.

"Underlayment failure is age"

Leaks under tile get blamed on old underlayment, so the whole claim is denied as wear and tear.

What we do: We show what the storm did to the tile above and how that let water through. Storm damage and an aging underlayment can both be true.

"Historic materials cost too much"

Older homes and churches need specialty tile and approvals, and the estimate doesn't cover either.

What we do: We price the real material and any historic district requirements, so the scope reflects what it takes to put the roof back the way it was.

What we look for

Photos from our own inspections. This is the kind of documentation that supports a re-inspection. Results vary; no claim outcome is guaranteed.

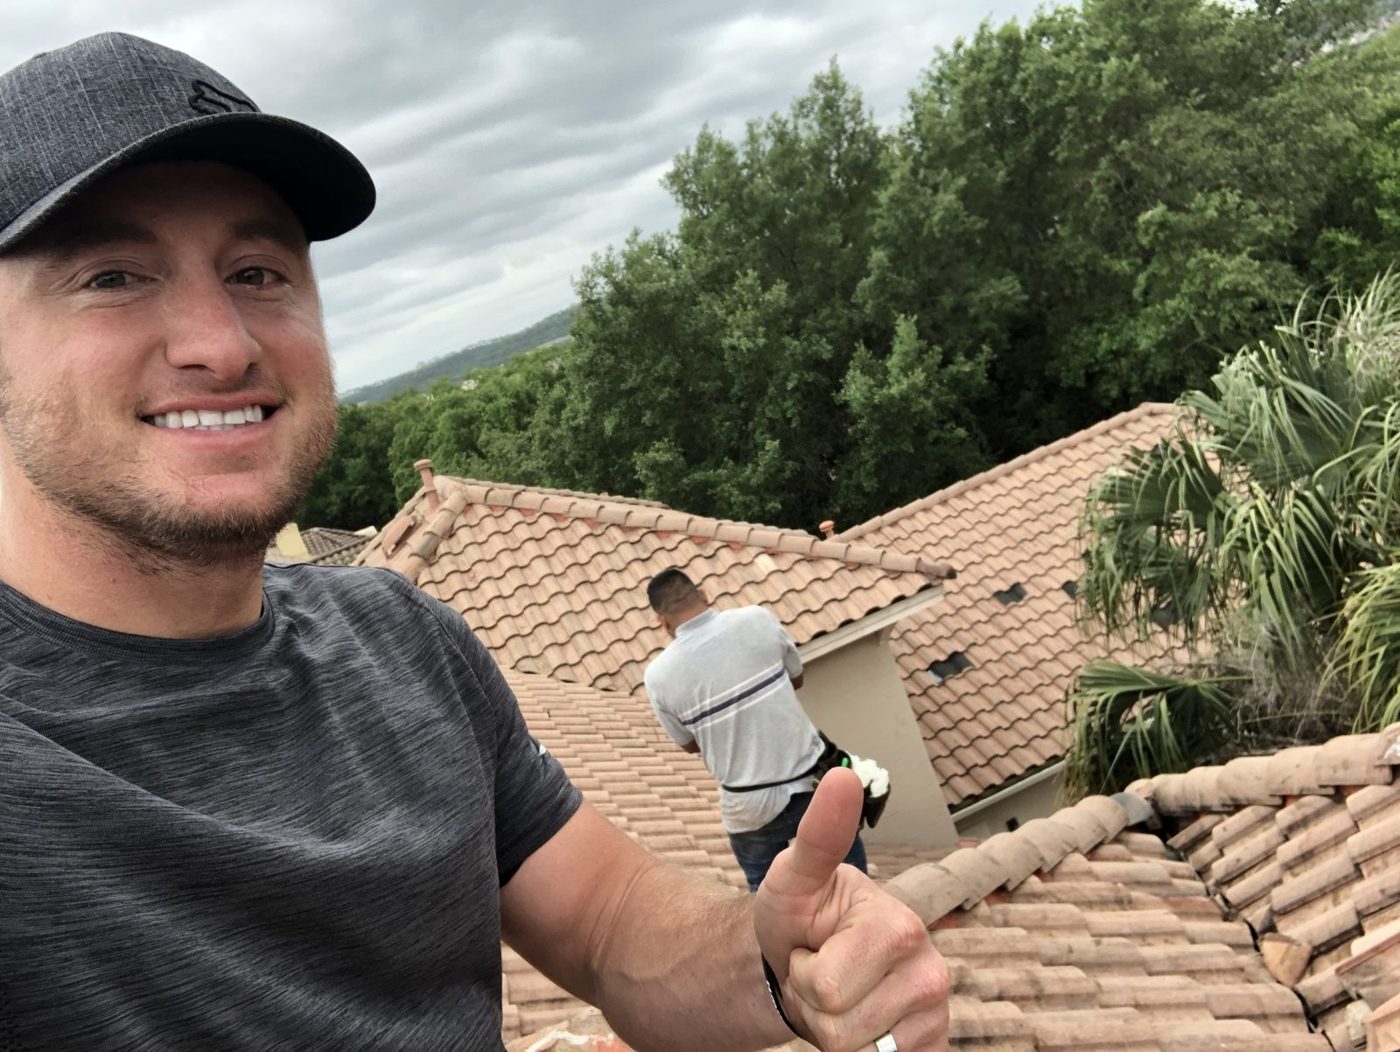
Inspecting a clay tile roof after a storm.
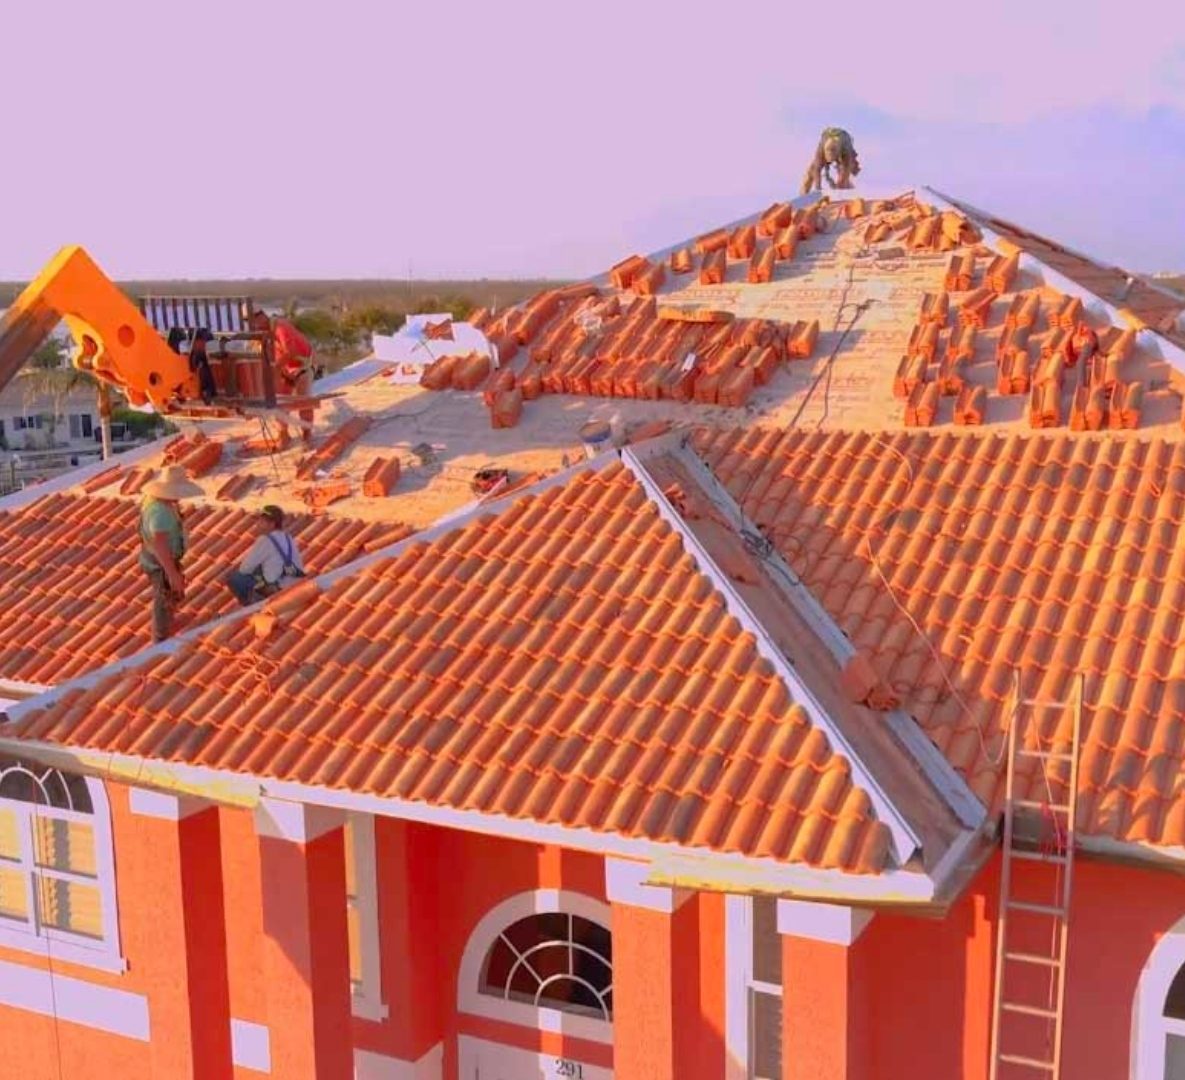
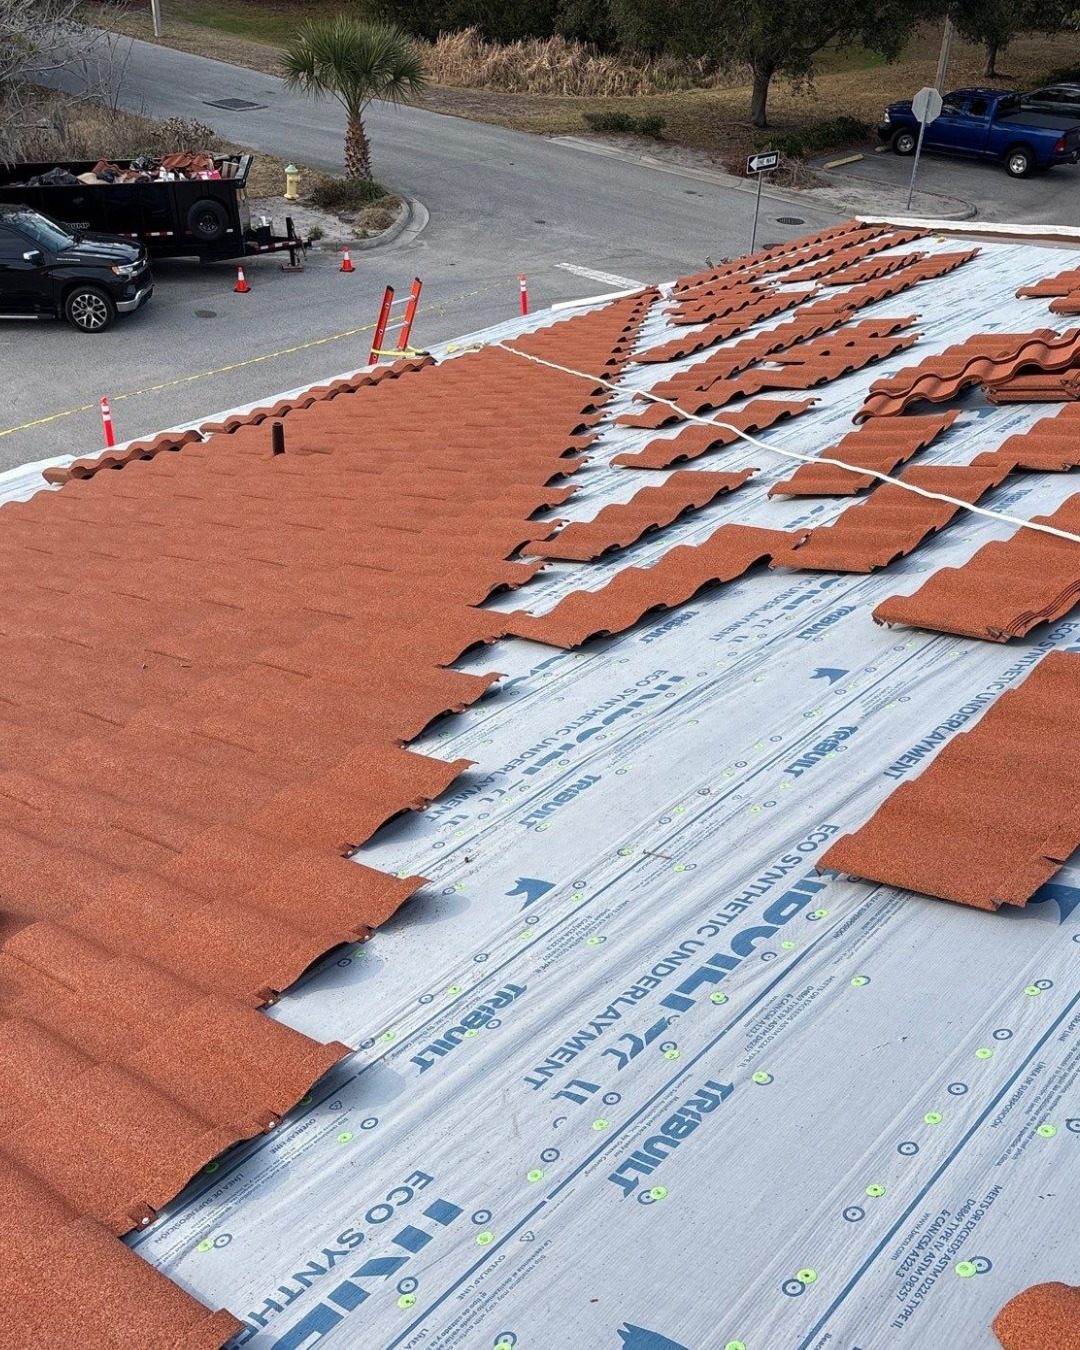
Tile removed and stacked for reinstallation during a restoration.
A historic clay tile home after restoration.

What we do

A denial letter is the insurer's first answer, not always the final one.

Send us your denial letter

Text a photo of the letter and your roof, or upload them on our contact form. We'll tell you what we see and what your options are.

We re-inspect and document

We go over the whole roof and build a report with photos, measurements and weather data that ties the damage to the storm.

You decide your next step

Depending on your policy, your options may include a re-inspection with the adjuster, a supplement, or the appraisal clause. We inspect, document and write the repair scope, and meet the adjuster on the construction scope. SkyView Restoration Group is not a public adjuster or law firm. You may hire any licensed public adjuster or attorney, or none.

Got a denial letter?

Send it to us with a few photos of your roof. A real person on our team will look it over and tell you where you stand. Asking is free. If you later sign a Project Agreement, its fee and cancellation terms are at SkyViewRestore.com/terms.

Call now Text a photo